OWN THE DIGITAL RELATIONSHIP
One modern digital experience for every customer — corporate and retail — across web, mobile, API and partner channels, over every product you run. Built once on the Digital Engagement Hub, launched one channel and one segment at a time, on the systems you already have.
To the customer, the channel is the bank. No corporate treasurer has ever seen a core banking system; no retail customer has ever met a loan management engine. They meet the app, the portal, the API — and everything the bank has built beneath is judged by what happens there. Banks spend fortunes modernising what customers never see, then deliver it through front-ends that undo the work. The engagement layer is where the institution is experienced, chosen and quietly re-chosen every day — and it is also the bank's distribution: every product the bank will ever launch reaches its customers only through this layer. Own it, and every investment beneath it finally shows. Neglect it, and none of them do.
The test is simple: does the customer experience the bank — or the bank's org chart?
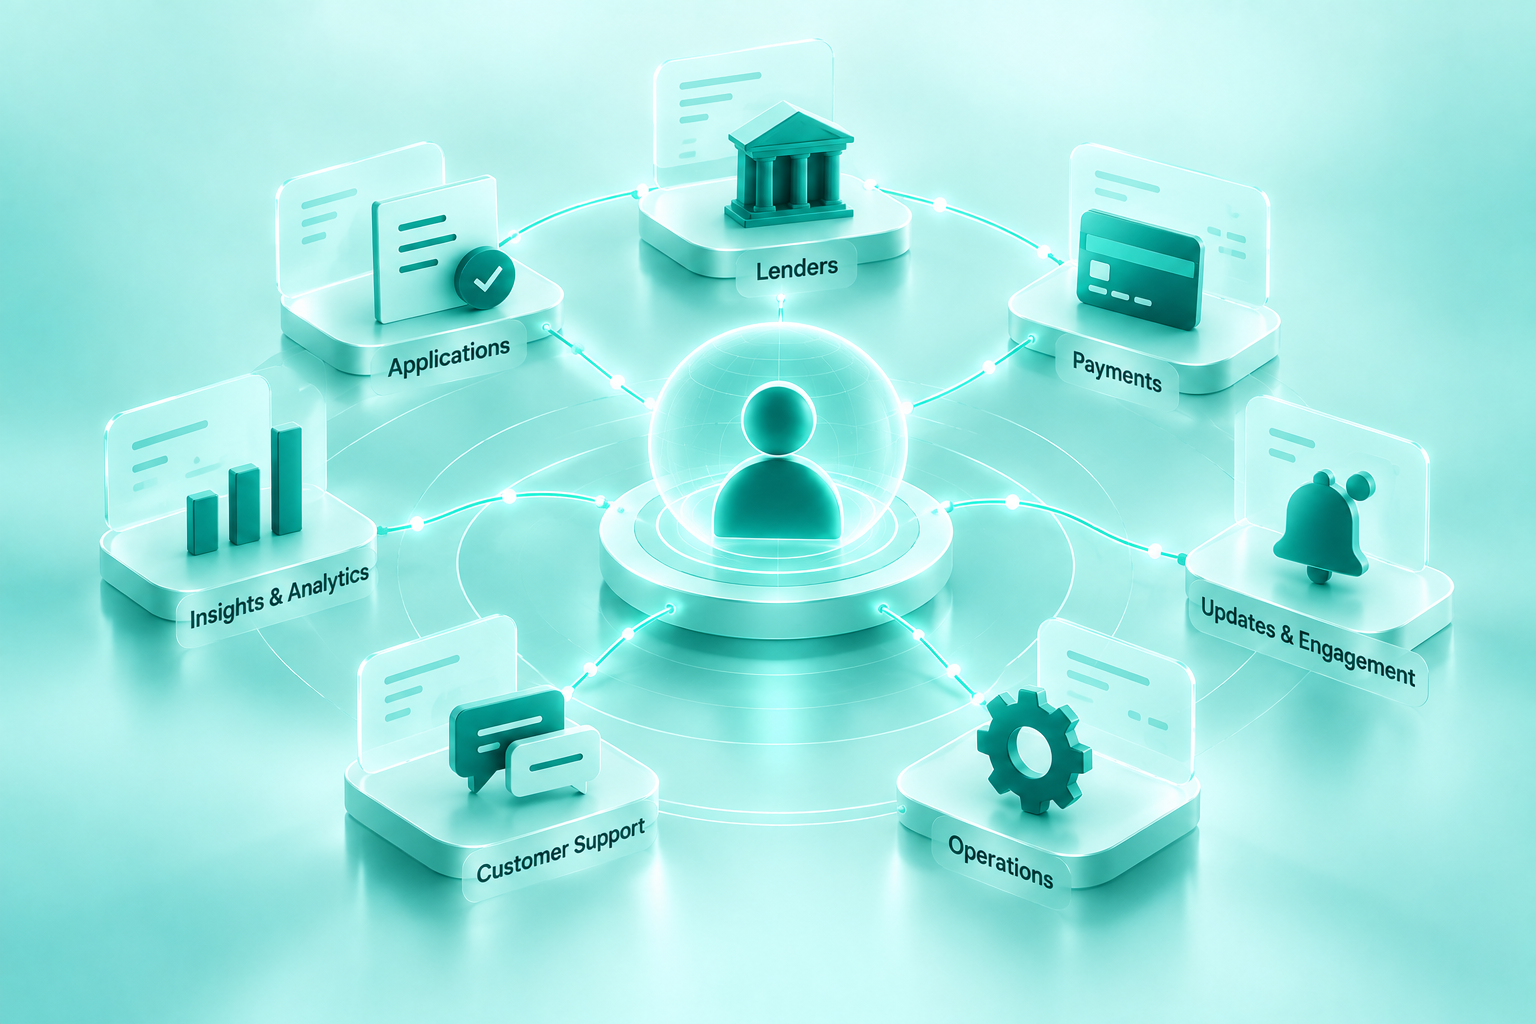
In practice: one login, recognised everywhere the customer touches the bank. A corporate treasurer runs cash, trade and financing through one coherent workspace; a retail customer banks, borrows and pays through one app — each getting the experience their world demands, from the same layer beneath. Products appear as one bank, not a portfolio of portals that happen to share a logo. And when the bank launches its next product, it lands in the channels that already exist — visible to customers on day one, not waiting for its own app to be built, tested and forgotten.
That is a digital relationship rather than a set of digital channels — and it is what customers now compare every bank against, because the best experience any of their providers offers becomes the standard all of them are held to.
Most banks' channel estates were never designed — they accumulated. A portal arrived with each product, an app with each segment, each with its own login, its own entitlements, its own design language and its own release calendar. The result is a fleet of front-ends that all do eighty per cent of the same work — onboarding, login, permissions, statements, notifications — each built, secured and maintained separately, at full price every time.
The customer pays differently. The customer can tell where one system ends and the next begins — a different password here, a different look there, a balance that means one thing in this app and another in that one. Inconsistency reads as disorganisation, and disorganisation erodes exactly the confidence a bank exists to project. Meanwhile every new product waits for its own front-end to be built before a single customer can touch it — so the channel estate doesn't just cost too much; it slows the whole bank's time-to-market. The org chart, shipped.
RULING RECORDED — Victor enters page copy, scoped: superseding the v128 note (c) and narrowing the v46–48 treatment for this page only, Victor is named in this umbrella's §5 — as the live demonstration of SuperDash's conversational intelligence ("you have already met it"), exactly the site-synergy §3 of this Constitution sanctioned. Victor remains the site-wide assistant everywhere else, is still never the hero of Digital Lending product copy, and SuperDash remains the named intelligence layer; this is a scoped spend of the demo synergy on the one page whose subject is the engagement layer itself.
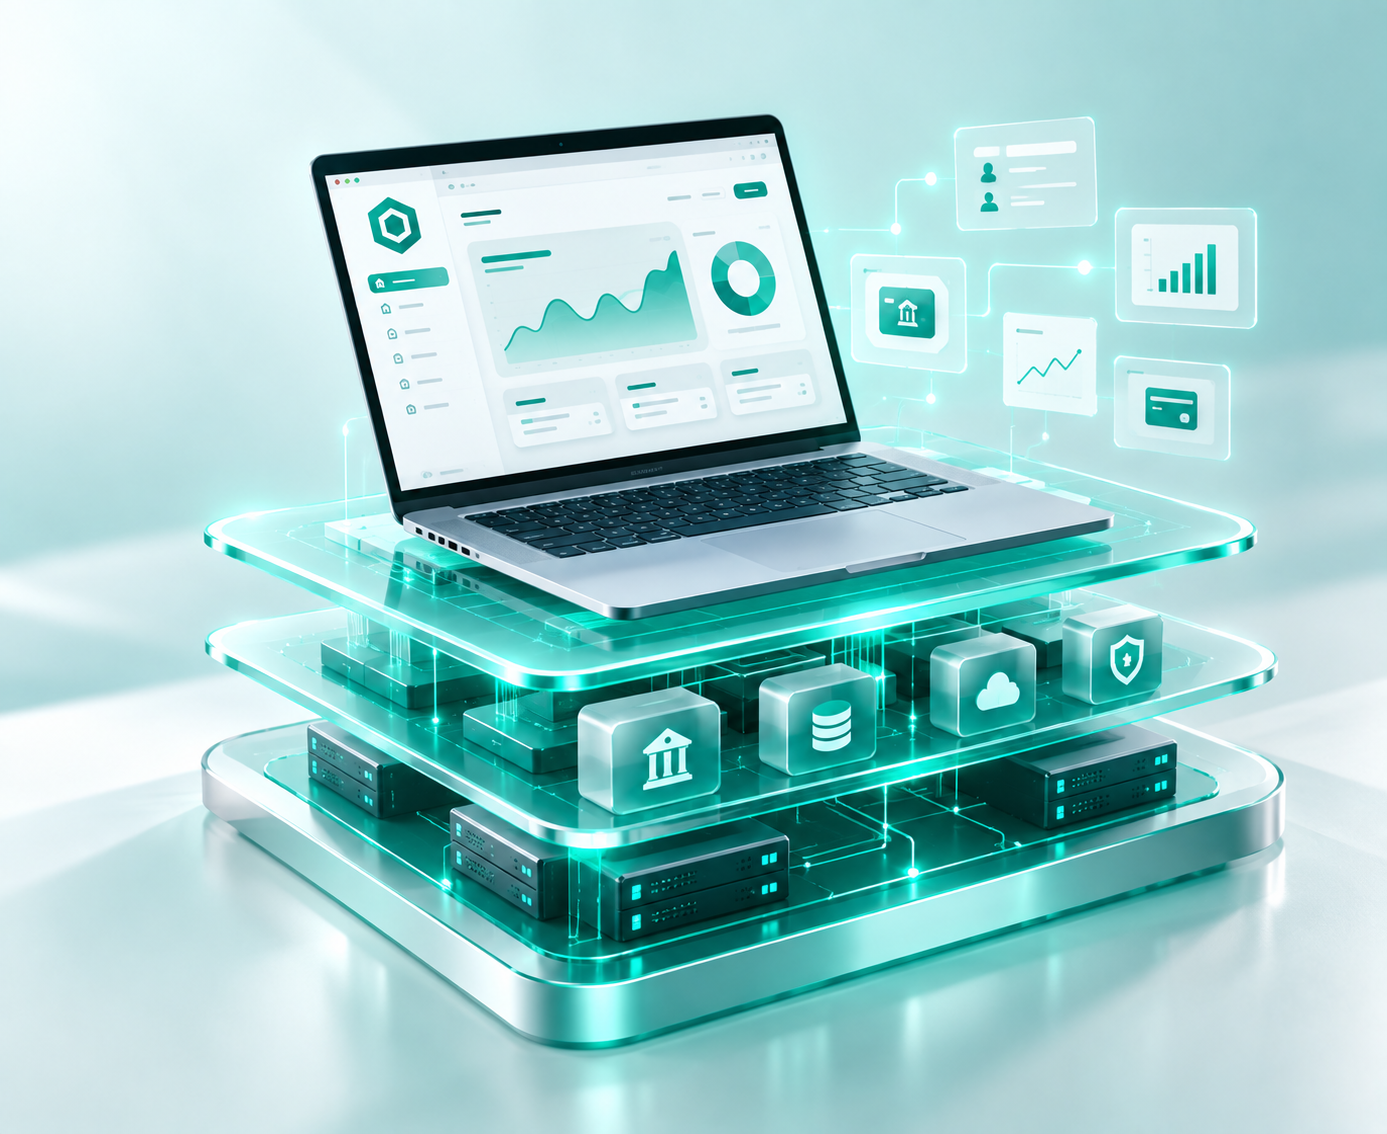
Veefin's answer is the Digital Engagement Hub — the experience layer of Veefin 4.0. The work every front-end repeats — onboarding, login and entitlements, dashboards, documents, notifications — is built once in the layer and expressed through every channel: web, mobile, API, partner. Corporate and retail run on the same layer with different experiences: the treasurer's workspace and the retail app are two faces of one foundation, not two systems maintained apart. API and embedded finance are first-class channels beside web and mobile, so the bank can be present inside its customers' own software, not only on its own screens.
And interaction itself is changing: customers increasingly expect to ask, not navigate. SuperDash brings conversational intelligence into the channel — ask a question, give an instruction, get it done. In fact, you have already met it: Victor, the assistant on this website, runs on the same conversational intelligence. The capability this page describes is the one you can try before the first workshop — on the site that sells it.
Launched one channel and one segment at a time, on the systems the bank already runs — the engagement layer wraps the estate a bank has; it does not demand a new one.

the corporate access layer: entitlements, makerchecker, multi-entity workspaces — the corporate stack's own story told at Modernise Transaction Banking.

the retail relationship end to end: everyday banking, borrowing, payments, self-service.

the bank present inside its customers' systems and its partners' journeys.

distribution beyond the bank's own screens.

one front door and one permission model, for every customer type. Beneath all five sits the Digital Engagement Hub — one layer, every channel, every product.
The model this page describes is not a concept awaiting its first believer. Digital banks run several Veefin products through one digital experience today — one login, one customer record, one experience across products — the one-relationship model live in institutions that were built digital-first, and available to every institution becoming so. In production across Asia, Africa and the Middle East, on the architecture beneath every Veefin product.
The digital relationship is one mandate with several owners — and the same engagement layer answers each of them.
| Role | What they're after |
|---|---|
| Chief Digital Officer | One digital relationship across every customer and product — engagement as infrastructure, not a project per product |
| Head of Digital Banking / Channels | Channels launched and evolved from one layer — consistent, faster to ship, measured in one place |
| Head of Corporate Internet Banking | A corporate workspace worthy of the operating relationship — entitlements, maker-checker, multi-entity, one login |
| Head of Retail Banking | A retail experience that competes with the best app the customer owns — banking, borrowing and paying in one place |
| CIO | One experience layer over the existing estate — one layer to secure, govern and evolve instead of a fleet of frontends |
Everything a bank builds arrives at one place: the screen in the customer's hand. The banks winning the digital relationship are not the ones with the most apps — they are the ones whose customers experience everything the bank does as one thing, done well. That is not a design preference; it is where loyalty now lives. Build the engagement layer once, run every customer and every product through it, and each new launch strengthens the experience instead of fragmenting it. The bank the customer experiences is the bank the customer keeps.