DELIVER THE RETAIL EXPERIENCE
Everyday banking, the whole lending shelf and self-service in one retail experience — joined in minutes, conversational by design, white-label ready — built on the engagement layer and grown one product at a time.
Retail customers no longer grade a bank's app against other banks' apps. They grade it against everything they use every day — the messaging, the shopping, the streaming — and they forgive nothing. That is the standard now, and most banking apps lost to it by default. But the bank starts this contest with assets no app company owns: the customer's trust, the deposit relationship, and a product shelf that runs from the everyday account to the home loan. What has been missing is the experience that delivers those advantages. Meet the phone's standard, and the trust and the shelf do the rest.
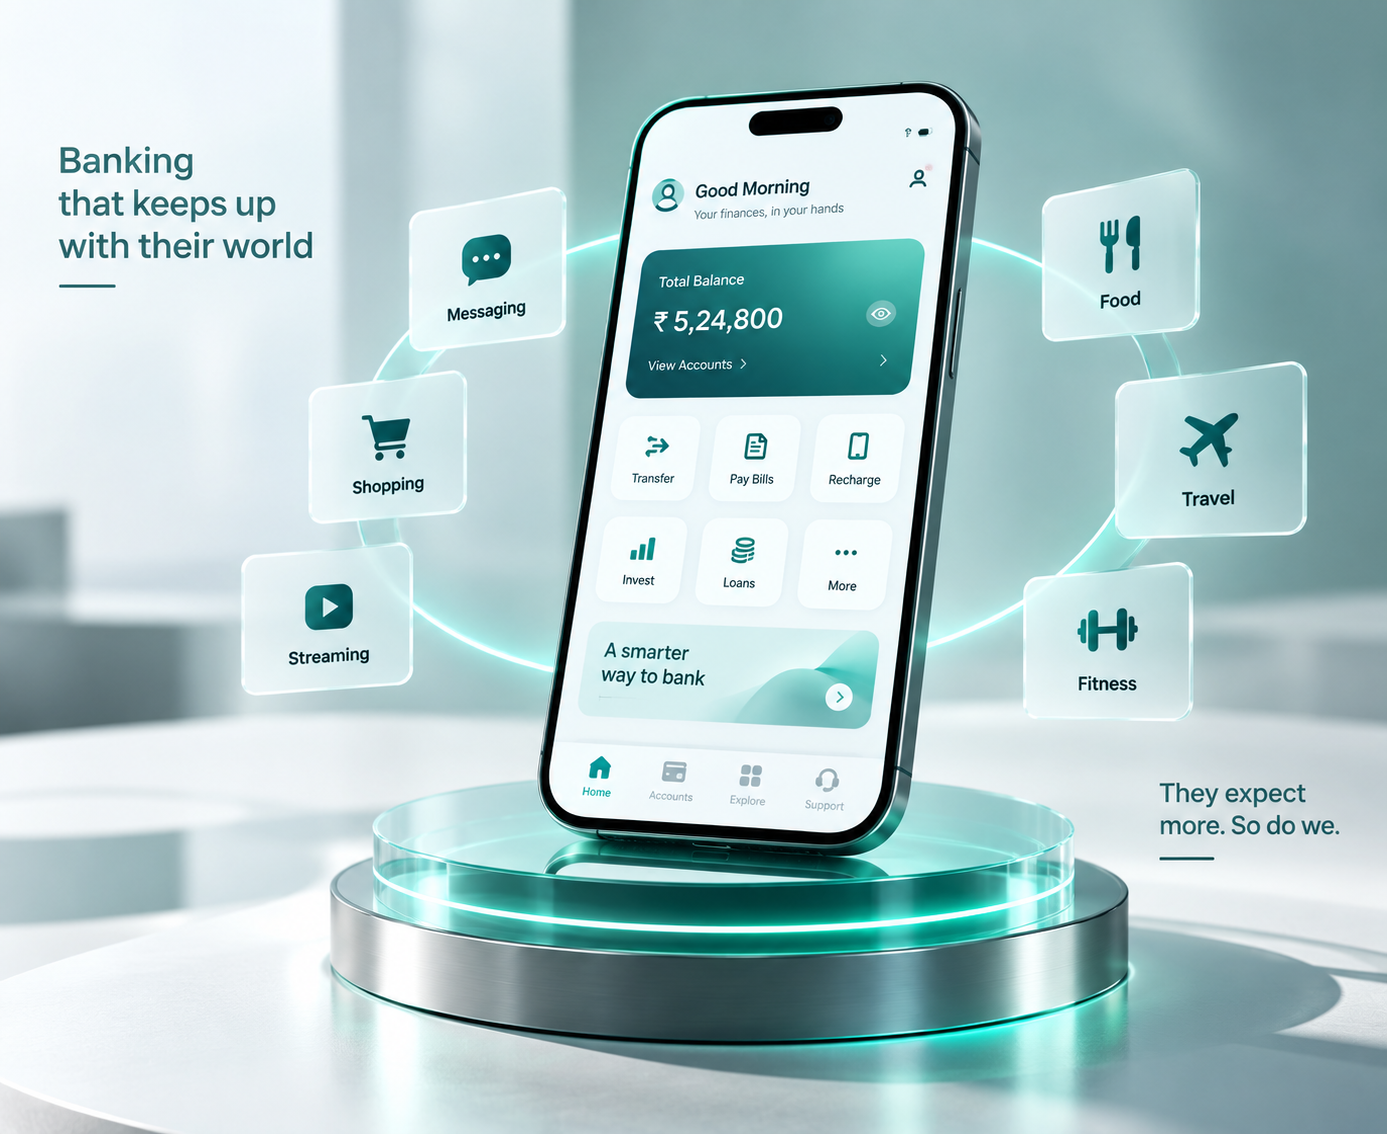
One retail experience over everything the bank offers — joined in minutes, used daily, grown one product at a time.

The front door decides everything after it. Digital onboarding with verification from data, adaptive forms that ask only what verification genuinely needs, and journeys that resume on any device. The front door stops being the drop-off point.

Habit is the retail franchise. Accounts and balances, payments and transfers, cards, alerts and statements — fast, consistent, always on. The daily check-in happens in your app — and the daily habit is the relationship.

Most banking apps stop where lending begins. On Veefin, the bank's whole retail lending shelf lives in the app — personal, home, vehicle, cards, gold and modern products alike — applied for, approved and serviced digitally, on the same lending stack the bank runs behind it. Every lending product the bank offers, one tap from the balance the customer already checks.

Service is where apps lose the goodwill onboarding won. Requests raised and tracked to completion, documents uploaded and delivered, communications in one place — resolved in-app, at any hour. Service at digital cost, satisfaction at branch standard.
Delivered across mobile, web and API, whitelabel ready · ISO 27001 and SOC 2 · VECTOR low-code integration into core banking and the bank's lending systems.
Retail banking is becoming something you ask, not something you navigate. Through SuperDash, the app converses: what did I spend on groceries this month? · pay the electricity bill · move ten thousand to savings — answered and done, inside the customer's authentication and limits, never outside them. Alerts and nudges work from behaviour — the balance about to run short before a scheduled payment, the deposit sitting idle — raised as service, not as noise. And you have already met the capability: Victor, the assistant on this website, runs on the same conversational intelligence the app carries.
The consequence: the app stops being a menu of functions and becomes a conversation with the bank — which is exactly the standard the phone set.
The app is the retail face of the Digital Engagement Hub — the experience layer of Veefin 4.0, the same layer that gives corporates their workspace. Onboarding, entitlements, communications and documents are built once in the layer and expressed for retail life; the experience is white-label ready, carrying the bank's brand rather than a vendor's. And because the app sits on the layer rather than on any one product, the next product the bank launches lands in it on day one — no second app, no front-end project, no waiting.
The banks built most recently — digital banks, retail-first by construction — chose this model: several Veefin products running through one experience, one login, one customer record. The newest institutions in the market already run the way this page describes, and the same engagement layer is available to every bank becoming digital rather than born so. In production across Asia, Africa and the Middle East.
The retail experience is one mandate with several owners — and the same engagement layer answers each of them.
| Role | What they're after |
|---|---|
| Head of Retail Banking | An app that competes with the best the customer owns — banking, borrowing and paying in one place |
| Head of Digital Banking / CDO | One retail experience on the engagement layer — consistent, measurable, extended without a project per product |
| Head of Retail Lending | The whole lending shelf in the app — origination to servicing, one tap from the daily balance |
| CIO | The retail face of the same layer that serves corporate — one front-end estate to secure, govern and evolve |
The retail relationship now lives on a small rectangle of glass, contested daily by the best software on earth. Banks don't win that contest with more apps; they win it with one experience good enough to keep — everyday banking that is effortless, lending that is present at the moment of need, service that resolves itself. The advantages were always the bank's: the trust, the deposits, the shelf. The experience is how they finally get delivered. Your competition is the best app on their phone. Build the one they'd keep anyway.