DIGITISE ENTERPRISE LENDING
The whole discipline of enterprise credit — origination, structuring, monitoring, servicing and recovery — digitised on one borrower record, with intelligence in every step. Built for facilities, not just applications, and launched one product and segment at a time on the systems you already run.
Lending is the bank's largest earning asset — and in business banking, it is also the deepest position a bank can hold. The bank a business borrows from sees what no other bank sees: its cash flows, its seasonality, its stress and its growth, quarter after quarter. That visibility prices the next facility better, catches trouble earlier, and pulls the rest of the relationship in behind it — the operating account, the transaction flows, the owner's own banking. Yield is the headline, but the durable prize is position: the lender of record is the bank every other bank has to displace.
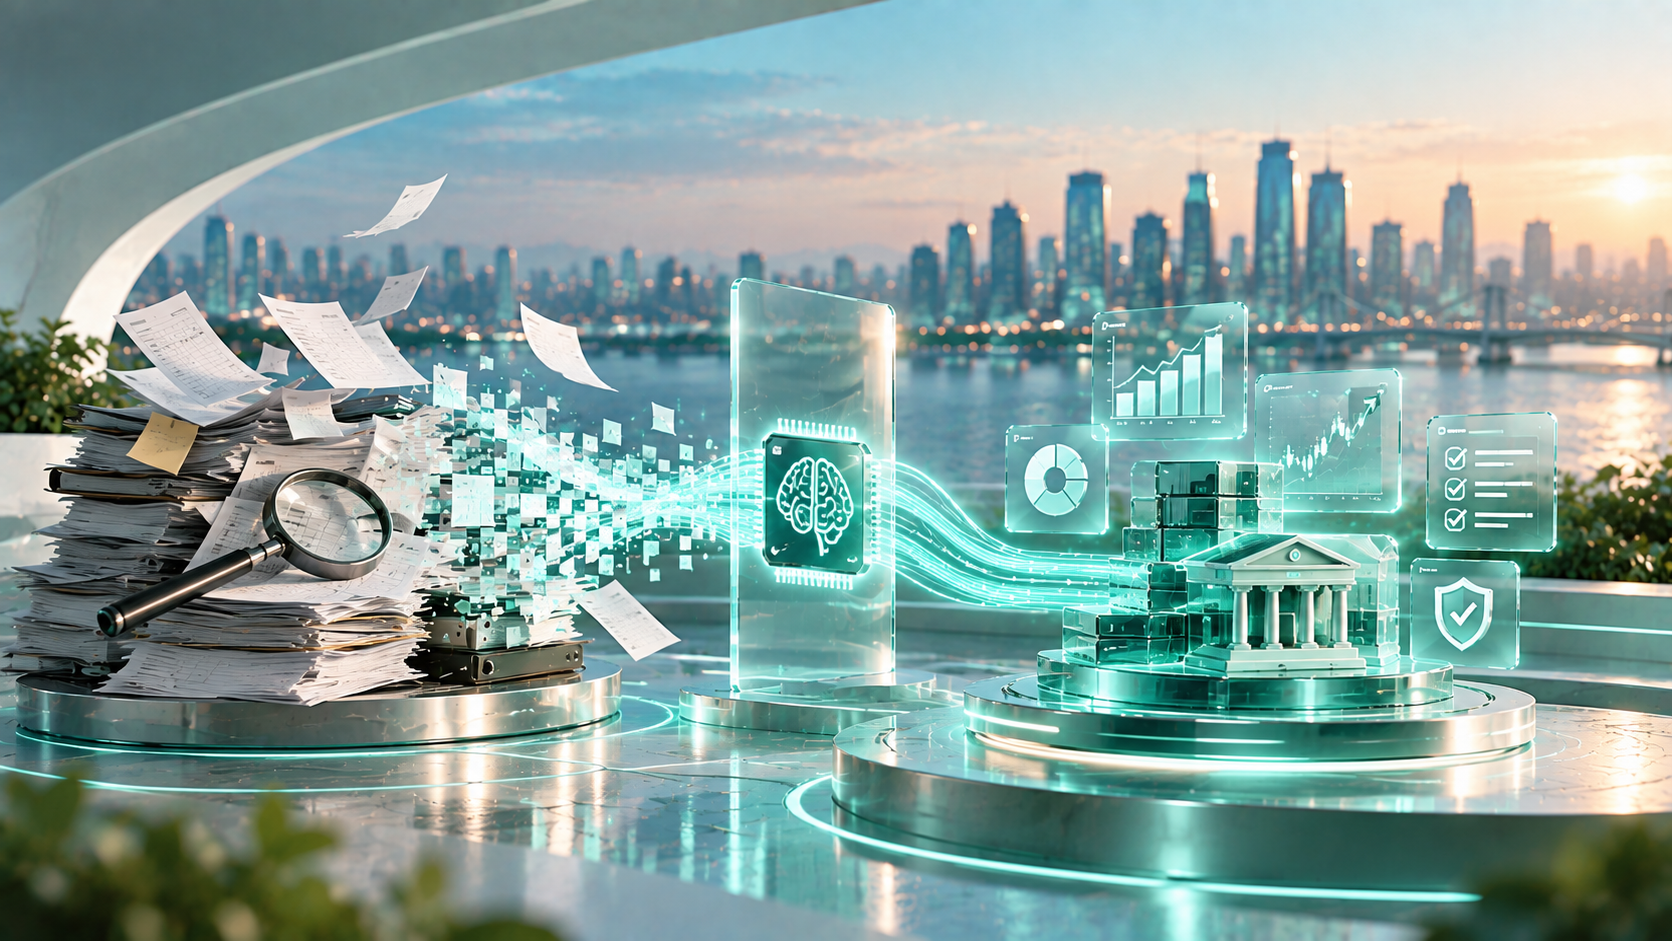
Most "digital lending" digitises the application — a form, a score, a disbursement. Enterprise credit is a different discipline: the judgement lives in appraisal, structuring, covenants and monitoring, and the money is made or lost across the life of the facility, not at the moment of onboarding. The target state is the whole discipline digitised — origination, management and recovery running on one borrower record, so the file that underwrote the loan is the same record that services it, watches it, and, when needed, collects it. One borrower. One lifecycle. One system of judgement.
The market is full of score-and-disburse engines relabelled as business lending — and they demo beautifully, because a demo is a clean case. A real enterprise facility is not. It is limits and sublimits, fund-based and non-fund-based, interchangeable as the business's needs move. Multitranche disbursements released against milestones and conditions. Collateral webs — multiple securities, shared charges, revaluations — that must stay attached to the exposures they secure. Covenants that live for years and must be tested, not filed. Committee approvals, delegation matrices and deviations that need a governed path, not an email chain. Annual renewals, enhancements, restructures — and, always, classification and provisioning the regulator will check.
A simple system handles the application and abandons the facility. The gap does not show in the pilot; it shows at the first real deal the structure cannot hold, and then every day after — covenants tracked in spreadsheets, limits reconciled by hand, renewals surfacing late, classification argued at audit. The credit-ops team quietly becomes the system, at the bank's cost and the CRO's risk. The system is the ceiling on the credit a bank can safely write — and in lending, the price of buying cheap is paid in basis points of NPA, discovered years later.
Digitising enterprise lending is not one project — it is one record, put to work three times. Everything origination learns — the financials, the securities, the sanctioned structure — is what servicing runs on. Everything servicing observes — repayment behaviour, utilisation, covenant performance — is what monitoring reads. And when an account turns, collections works from the full history, not a fragment. Each stage makes the next one better, because nothing is re-keyed and nothing is lost between systems.
And this is the lending discipline where intelligence now earns its place in the flow: credit appraisal memos generated from the file instead of assembled over days; bank statements and GST data read and analysed at machine speed; early-warning signals raised from behaviour while there is still time to act; repayment follow-up prioritised by likelihood, not alphabet. The judgement stays with the banker — the platform brings the judgement everything it needs.
None of it requires a big bang. Start where the pressure is — one product, one segment — prove it, then extend: the record, the policies and the integrations carry forward to every product that follows.
The lending stack on this page is in production — origination, management and collections — across banks and non-bank lenders spanning retail, MSME and corporate books. It sits within the platform of the #1-ranked provider on the IBSi Sales League Table for Wholesale Transaction Banking — which matters to a credit buyer for a specific reason: the same architecture that carries a bank's transaction business carries its lending, on one customer record. And the connected-lifecycle model this page describes is not a concept: institutions run origination, servicing and collections together on Veefin today, as one system.
Digitising enterprise lending is one initiative with several owners — and the same platform answers all of them.
| Role | What they're after |
|---|---|
| Chief Credit Officer / Head of Credit | Judgement digitised — appraisal, structuring, covenants and early warning governed on one record, defensible at audit |
| Head of SME & Commercial Banking | A segment finally worth its economics — digitised processing that makes MSME lending profitable at low cost-toserve |
| Head of Collections / COO | Recovery that runs on behaviour and the full borrower history — compliant, prioritised, and not a spreadsheet operation |
| CIO | One lending stack across retail, MSME and corporate, on the bank's existing systems — no parallel platforms per product |
The bank that holds a business's borrowing holds its story — and the position every other bank has to displace. Winning that position takes more than a digital application form: it takes the whole discipline of enterprise credit — structuring, monitoring, renewal, recovery — digitised on one record, with the judgement kept where it belongs. The simple tool digitises the journey and abandons the facility. The right platform digitises the judgement — and the book it writes is the proof. The system is the ceiling on the credit a bank can safely write. Choose the ceiling accordingly.