MODERNISE CREDIT DECISIONING & MONITORING
The whole life of a credit decision on one borrower record — appraisal on the full file, governed approval paths, facilities structured as the deal demands, and a book watched continuously rather than at month-end. Digitised one product and segment at a time, on the systems you already run.
The committee's yes is the shortest part of a credit decision. What follows lives for years: covenants that must be tested, limits that must hold, drawdowns released against conditions, renewals that come round annually, classification the regulator will check. Most "digital credit" digitises the moment of yes — the form, the score, the sanction letter — and leaves every day after to spreadsheets and memory. But the CRO answers for the whole life of the facility, and the book's risk accrues after sanction, not before it. Digitise the judgement end to end — appraisal through monitoring, on one borrower record — and speed and control stop being a trade-off. They become the same system.
One platform for the whole discipline of credit — built so a bank can digitise the judgement one product and segment at a time, not through a big-bang replacement.

Judgement is only as good as the file it starts from — and in most banks, the file is assembled by hand, over days. Veefin builds a single borrower file at intake: financial statements spread automatically, bureau reports pulled, bank statements and GST data captured, documents verified as they arrive — with thinfile assessment where formal financials run out. Judgement starts complete on day one, not assembled over days from attachments.

Approval time is won or lost in the path a proposal travels — and governance is why the path exists. A policy engine with drag-and-drop credit policies, versioned scorecards, delegation matrices that route each case to the right authority, committee workflows, deviation handling with a full audit trail — and instant decisioning where policy allows it. Faster approvals the bank can defend at audit — speed from the governed path, not around it.

An enterprise facility is a structure, not an amount. Limits and sublimits, fund-based and non-fund-based, multi-tranche disbursement against milestones and conditions, collateral linked to the exposures it secures with revaluation schedules, covenants captured as living, testable obligations. The sanctioned structure becomes the record the system enforces — not a memo about it.

After sanction, most banks watch the portfolio through reports that arrive after the fact. Veefin watches it as it moves: covenant testing on schedule, automated DPD tracking, NPA flagging and PAR classification on a configurable matrix, utilisation and repayment behaviour followed continuously, renewals surfaced early instead of discovered late. Trouble found while it is still cheap — and classification the bank never has to argue at audit.
Delivered across web, mobile and API, with maker-checker controls throughout · ISO 27001 and SOC 2 · VECTOR low-code integration into core banking, bureaus and data sources.
A credit team's day is spent producing judgement's raw material by hand: appraisal memos assembled over days from a dozen sources, bank statements read line by line, early warnings that arrive as month-end reports — after the month in which they mattered. On Veefin, that work moves at machine speed. Credit appraisal memos are generated from the file itself, ready for the analyst to challenge rather than compile. Bank statements and GST data are read and analysed in minutes, not afternoons. Early-warning signals are raised from live behaviour — utilisation drift, repayment stress, a covenant heading for breach — while there is still time to act, not after the quarter closes. And over the portfolio sits SuperDash, the conversational layer: ask which accounts are drifting, which renewals are due, where the deviations cluster — and act from the same screen.
The judgement stays with the banker. The platform's job is to hand that judgement a complete file, a live book, and the time to think.
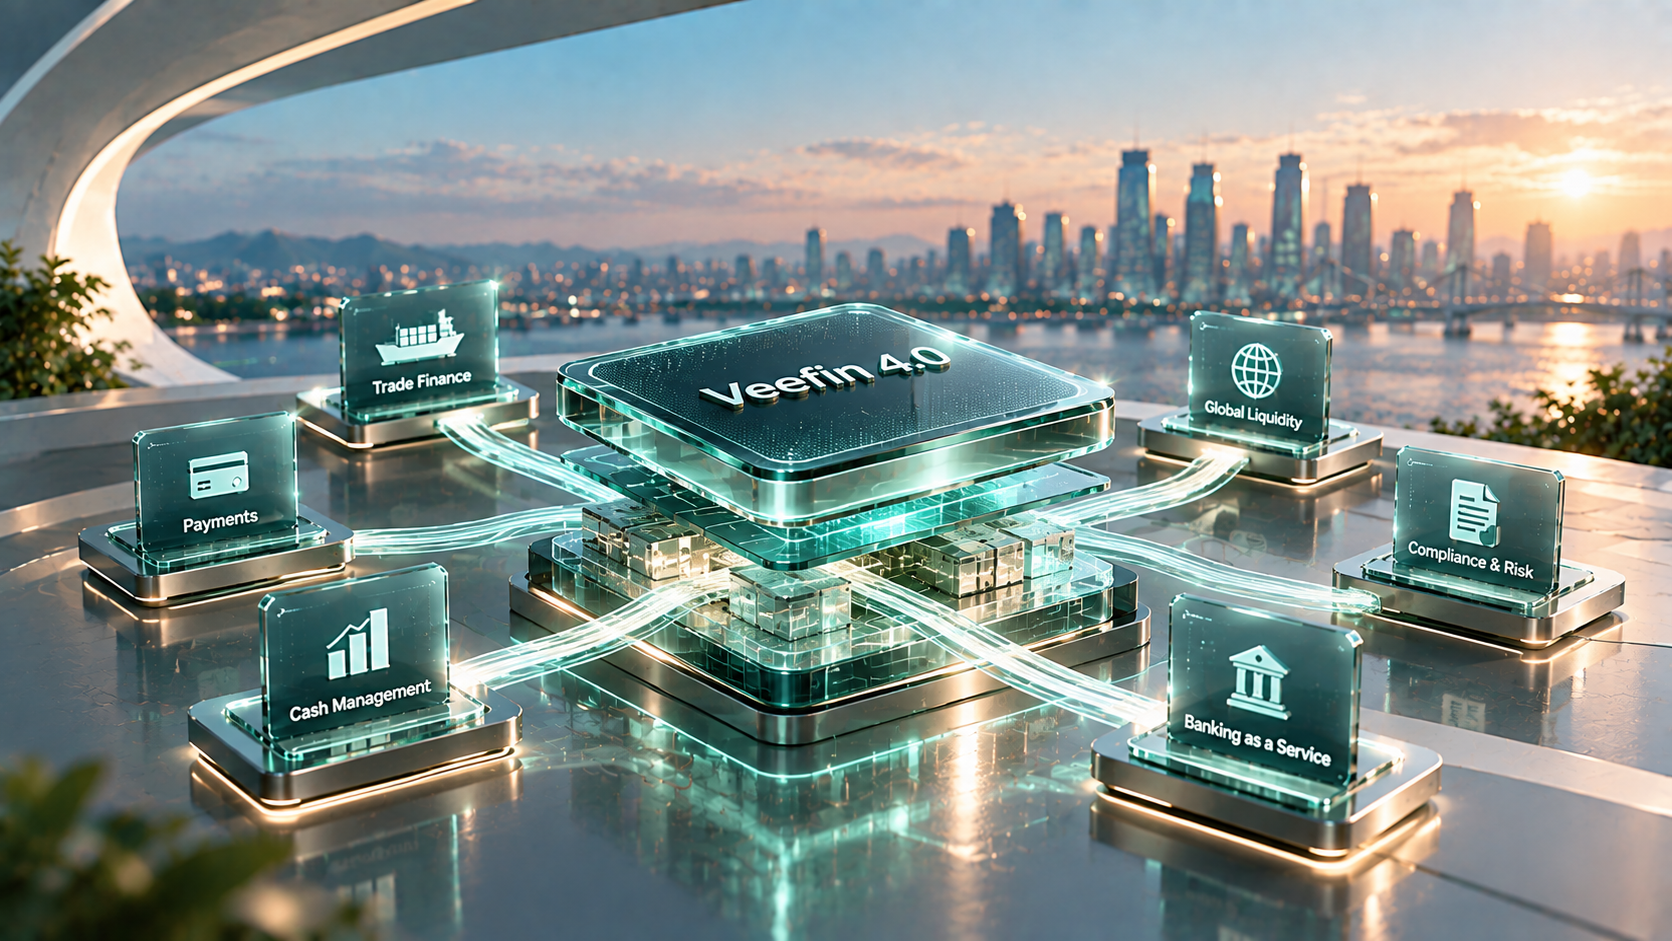
The reason speed and control can be the same system is architectural. The file that underwrites the loan is the record that services and watches it — nothing is re-keyed between origination and monitoring, so nothing is lost between them. Credit policies and scorecards are versioned once and inherited everywhere they apply, so a policy change reaches every journey the day it is approved. New credit products are configured on the product factory, not coded. And VECTOR connects the judgement to everything that feeds it — core banking, bureaus, the bank's own data sources — through low-code integration rather than a fresh project per system.
The decisioning and monitoring on this page are in production — across banks and non-bank lenders, on books spanning retail, MSME and corporate credit. Institutions run origination, servicing and collections together on Veefin today, as one system: the one-record architecture this page rests on is carrying live portfolios, not awaiting its first deployment. And it sits within the platform of the #1-ranked provider on the IBSi Sales League Table for Wholesale Transaction Banking — which matters to a credit buyer for a specific reason: the architecture a bank trusts with its transaction business is the architecture watching its book.
Modernising credit decisioning is one mandate with several owners — and the same platform answers each of them.
| Role | What they're after |
|---|---|
| Chief Credit Officer / Head of Credit | Judgement digitised end to end — appraisal, sanction, covenants and classification governed on one record, defensible at audit |
| Head of Corporate & Commercial Credit | Deals structured as sanctioned and enforced as structured — yes to complex facilities without losing the file |
| COO / Head of Credit Operations | The file assembled once and the book watched continuously — credit operations out of spreadsheets and month-end |
| CIO | Decisioning and monitoring integrated to the systems the bank already runs, through one low-code layer — no parallel credit stack |
Credit is the discipline where speed is usually bought with risk — approvals accelerated by thinning the file, loosening the path, or watching less. That trade-off is not a law of banking; it is a property of fragmented systems. Put appraisal, decisioning, structuring and monitoring on one borrower record, and the same platform that shortens the path to yes is the one testing covenants and reading behaviour every day after. Faster because it is governed. Safer because it never stops watching. A credit decision lives as long as the facility. Now the system that made it does too.