UNLOCK MSME LENDING
MSME lending that pays at bank standards — digital onboarding, files judged on how the business actually trades, straight-through decisions where policy allows, and servicing at digital cost. Launched one product at a time, on the systems you already run.
Every bank wants the MSME segment. It is vast, underserved, and pays properly for risk properly judged — and the demand never stops arriving. What fails is the arithmetic: a small loan processed manually costs the bank nearly as much as a large one, and the file behind it is too thin to judge cheaply by traditional means. So banks ration the segment — not because the businesses aren't creditworthy, but because finding out is too expensive. That is the real blocker, and it is a systems problem, not a segment problem. Fix the cost of judgement, and MSME lending stops being the book a bank apologises for and becomes the one it grows — profitably, and at the bank's own credit standards.
MSME lending fails or works at four points of cost. Veefin is built to collapse each of them — launched one product at a time, on the systems you already run.

The first cost is acquisition: branch-andpaperwork origination prices small tickets out before judgement even begins. Digital application journeys with adaptive forms, OCR document capture and validation, resume on any device; DSA/DST field apps for assisted sourcing; partner and API-sourced origination; bulk onboarding where programmes demand it. Acquisition at digital cost — so branch economics stop deciding who gets a loan.

MSMEs fail traditional appraisal not because they aren't creditworthy, but because the paperwork asked of them was designed for corporates. Bank-statement analysis, GST data, bureau reports, cash-flow-based scorecards and thin-file assessment, with documents verified at intake. The business judged on how it actually trades — not on the paperwork it was never built to produce.

At MSME volumes, every manual touch is margin. A policy engine with versioned scorecards, instant decisioning where policy allows, straight-through processing for the clean majority, and governed deviation paths — with a full audit trail — for everything else. A yes in the timeframe the borrower will wait, at a marginal cost the ticket size can carry.

The economics are lost after disbursement as often as before it. Automated servicing across the lifecycle, borrower self-service, digital-first reminders and self-cure journeys, and behaviour-based prioritisation when accounts slip. The back book stops eating the front book's margin.
Delivered across web, mobile, API and assisted field channels · ISO 27001 and SOC 2 · VECTOR low-code integration into core banking, bureaus and data sources.
In corporate credit, machine-speed analysis saves the credit team time. In MSME lending it does something more fundamental: it makes judgement affordable at all. An analyst reading bank statements line by line costs the same whether the ticket is large or small — which is precisely why small tickets went unjudged. On Veefin, the reading runs at machine speed: bank statements analysed in minutes, GST filings turned into a picture of how the business actually trades, bureau data blended with cash-flow behaviour, and scorecards applying the bank's own policy to files a manual process would have declined unread. Over the portfolio sits SuperDash, the conversational layer: which segments are performing, where early stress is clustering, which programmes deserve more capital — asked and answered in the flow of work.
The judgement stays with the banker. The intelligence doesn't lower the bar — it lowers the cost of applying it.
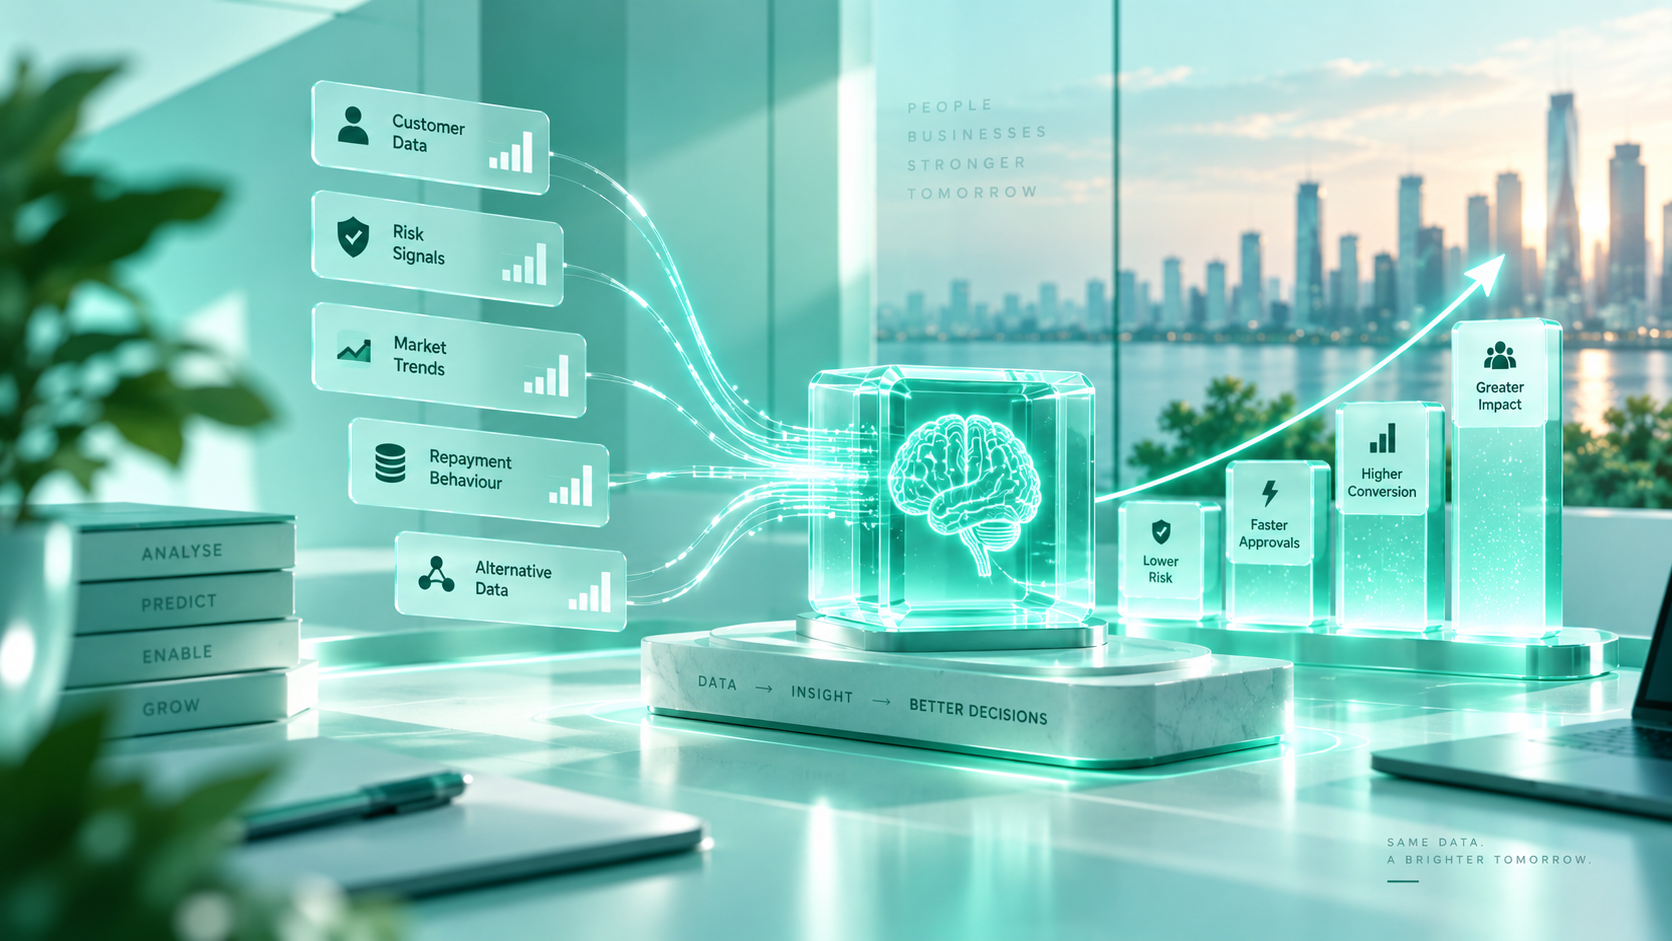
The wrong way into MSME lending is a parallel stack — a point "SME tool" bolted beside the bank's real systems, with its own borrower record, its own policies and its own reconciliation burden. On Veefin, MSME is a segment, not a separate system: the same borrower record, the same policy engine and the same servicing and collections machinery that run the rest of the lending book, with segment products configured on the product factory in days rather than coded in quarters. And when the segment grows, nothing needs replacing — the stack was the bank's stack from the first loan.
MSME lending punishes unproven systems at volume — so proof has to come at volume. Veefin is the platform behind $45B+ in disbursements, processed across banks and non-bank lenders, with origination, servicing and collections in production on books spanning retail, MSME and corporate credit. Institutions run the connected lifecycle this page describes today, as one system. And it sits within the platform of the #1-ranked provider on the IBSi Sales League Table for Wholesale Transaction Banking — the architecture judging small files is the same one large institutions trust with their transaction business.
Unlocking the MSME segment is one ambition with several owners — and the same platform answers each of them.
| Role | What they're after |
|---|---|
| Head of SME / MSME Banking | A segment finally worth its economics — growth at digital cost-to-serve, at the bank's own credit standards |
| Chief Credit Officer / Head of Credit | Thin files judged, not waved through — cash-flow scorecards, straight-through processing inside policy, and a full audit trail |
| COO / Head of Operations | Volume without headcount — onboarding, servicing and follow-up that run digitally, with people on exceptions only |
| CIO | A segment launched on the bank's existing lending stack — no parallel SME system to integrate, reconcile and one day replace |
Every bank has looked at the MSME segment and seen the same thing: the demand is real, the margins are real, and the economics don't work by hand. That is the whole story of MSME lending — and it has a systems answer. Digitise the journey, judge the file by how the business trades, decide straight-through where policy allows, serve the book at digital cost — and the segment every bank rations becomes the book the bank grows. The banks that win MSME won't be the ones that took more risk. They'll be the ones that could afford to judge it. The problem was never demand. Now the cost of judgement doesn't have to be the problem either.