FINANCE THE SUPPLY CHAIN
Payables, receivables and channel finance — every programme structure, from reverse factoring to deep-tier and Sharia-compliant variants — engineered for single-file, industrial-scale volume. One anchor mandate, a whole chain of business, launched one programme at a time on the systems you already run.
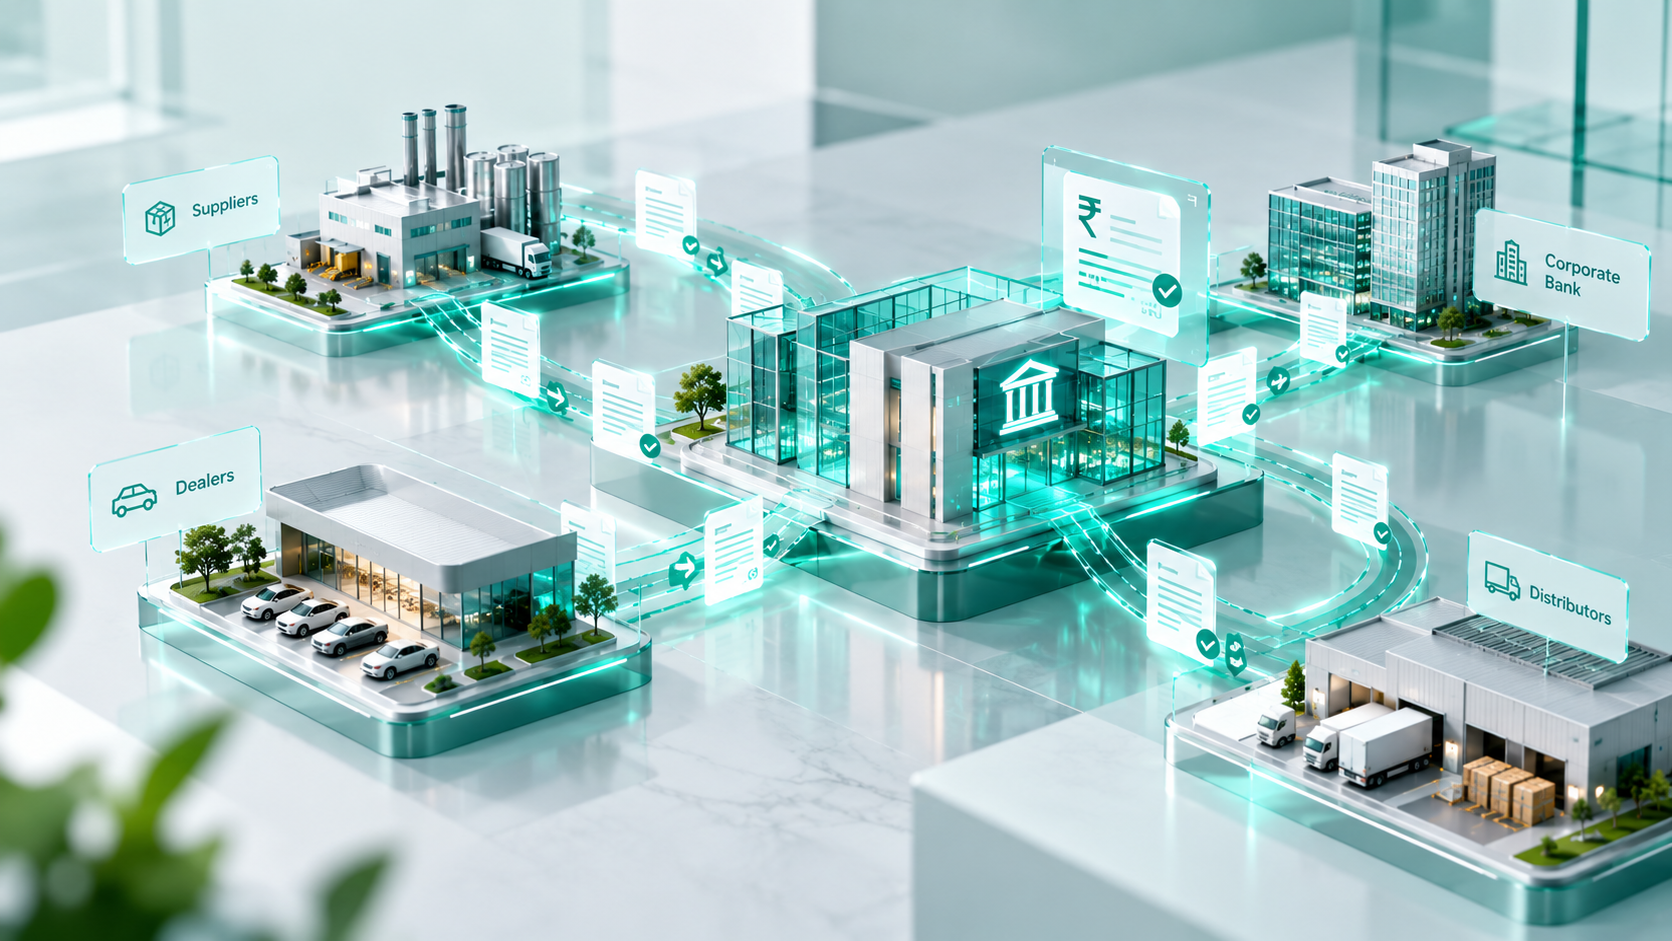
The corporate the bank already banks sits at the centre of hundreds of suppliers, dealers and distributors — and every invoice moving between them is a financing opportunity the anchor's own data de-risks. This is the multiplication move in transaction banking: one anchor mandate opens a book of assets, balances and fee income across counterparties the bank could never profitably acquire one by one.
But here is what the market persistently gets wrong: SCF looks simple from the outside. An invoice, an early payment, a discount — how hard can it be? In practice, no two programmes are alike. Who bears recourse, and when it shifts. How the tri-party agreement allocates obligations. Sub-limits by counterparty, tenor and margin structures by segment, interest borne by anchor or by spoke, disclosed or undisclosed assignment, multi-lender participation, Sharia-compliant variants. The structuring is where the economics live — and where the risk lives. Programmes that run on a simple system work in the pilot and fail at the first structure the anchor actually asks for; the gap only becomes visible when the deal that would have grown the book cannot be built. The system a bank chooses is the ceiling on the programmes it can sell — which is why buying SCF on price is the one decision this business punishes most reliably.
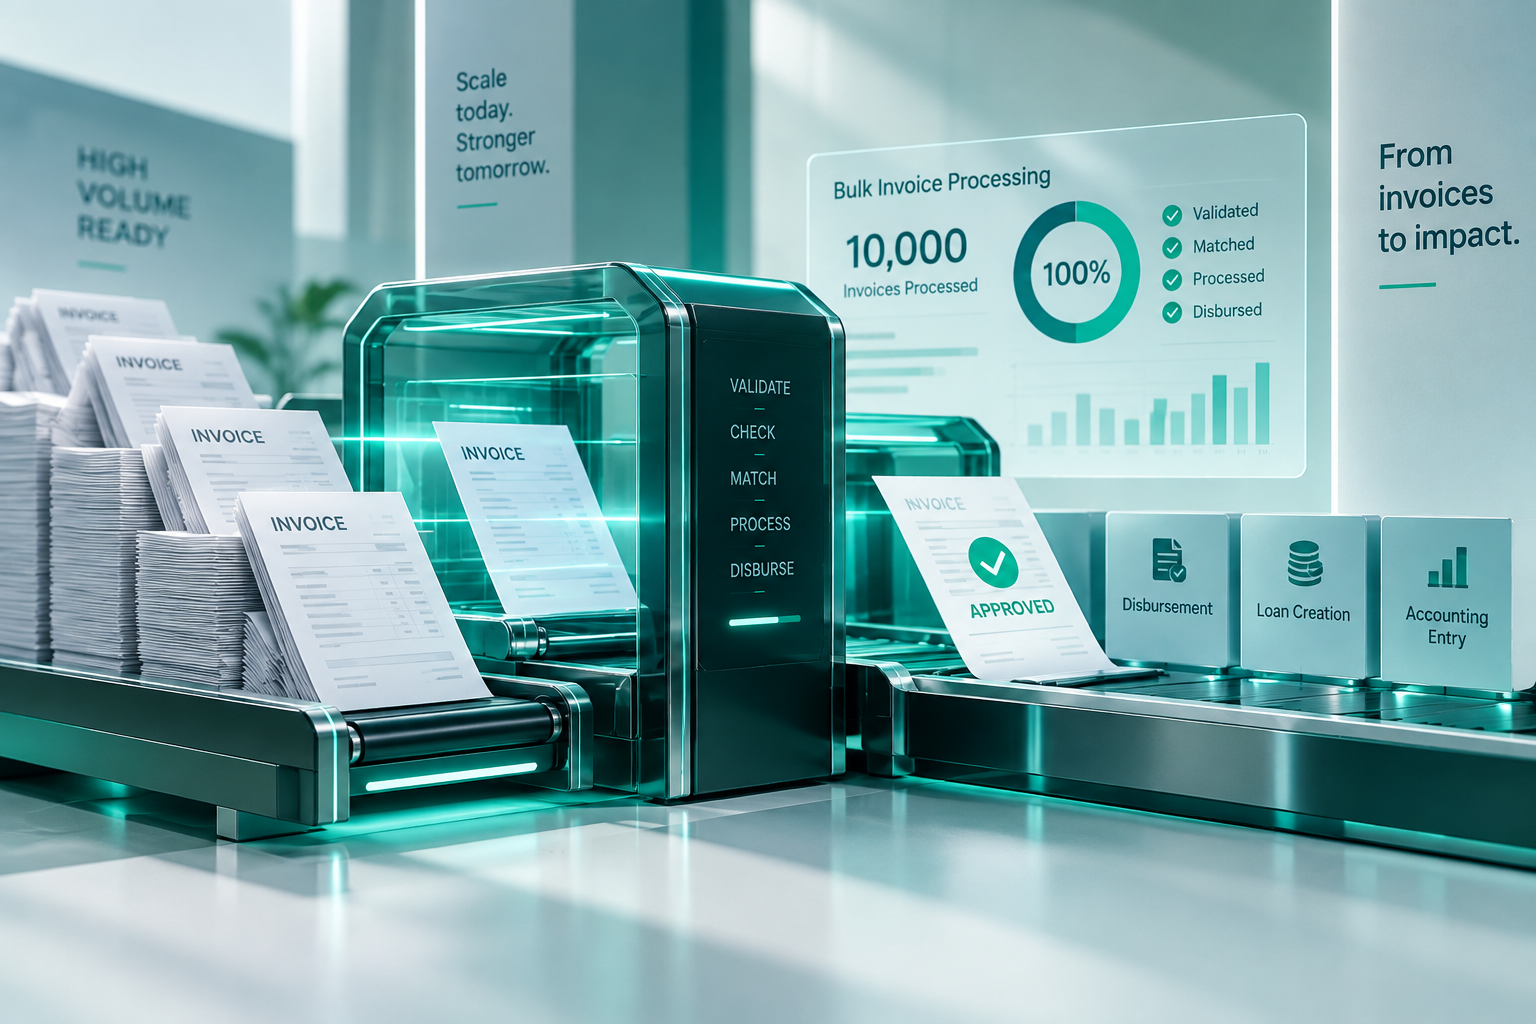
And structuring is only half of what the system must survive. SCF is an industrial-volume business moving serious money: ten thousand invoices can arrive in a single file upload — and every one of them becomes a disbursement, a loan on the book, an interest accrual and a repayment to be matched, all triggered in one shot, against the anchor's ERP over live API connections. At that volume, small failures compound into large losses fast: a duplicate invoice financed twice, a missed API call that drops a batch, a reconciliation break that lets repayments pile up unmatched, month-end accruals drifting from the ledger — each invisible at ten invoices, each expensive at ten thousand. This is not software that can be "mostly right." In SCF, the error rate ships in bulk — and the platform is either engineered for that volume, or the operations team becomes the system, at the bank's cost and risk.
Every programme family, and the structuring range inside each — so the bank says yes to the deal in front of it, and launches it one programme at a time on the systems it already runs.

Reverse factoring, approved and confirmed payables, dynamic discounting, vendor finance — early-payment, materials and capex variants — structured around the anchor's terms: who pays the discount, when title passes, how limits sit. The bank that can hold the anchor's structure wins the anchor's programme — and the anchor brings its suppliers with it.

Factoring with and without recourse, notice-ofassignment and undisclosed structures, invoice discounting through to deep-tier, receivable purchase. Recourse, disclosure and tier are the levers that make a receivables deal bankable — a system that holds them all means fewer deals turned away.

Dealer and distributor finance — floor-plan and stock structures — purchase-order finance from work-order to milestone, pre- and post-shipment finance. Channel finance is where the anchor's sales growth becomes the bank's asset growth, structured around how the channel actually buys and sells.

Two-tier onboarding for anchor and counterparties, KYC and AML screening, duallevel credit scoring, AI-driven financial spreading, fraud and duplicate-invoice detection, sampled post-disbursement audit. Scale is only profitable when risk is industrialised — this is the machinery that lets one programme carry a thousand counterparties safely.
Islamic structures — Murabaha and Tawarooq — run as first-class programme variants, not adaptations.
Delivered across web, mobile, API and host-tohost · ISO 27001 and SOC 2 · VECTOR low-code integration into the anchor's ERP, core banking and payment rails.
An SCF programme is judged on its worst file, not its best demo — and the worst file is not a busy day, it is one upload: thousands of invoices hitting the system at once, each needing validation, disbursement, loan creation and accounting before the anchor's suppliers are watching their banks. The platform is built for exactly that burst: bulk ingestion with validation at the gate — duplicates, anomalies and mismatches caught before money moves, not found in month-end; straight-through processing from approved invoice to disbursement to loan creation, each with its accounting entries posted as it happens; automated matching of repayments to invoices to loans, so reconciliation is an exception queue, not a department; resilient ERP and API connectivity that queues, retries and reports rather than silently dropping a batch; and sampled postdisbursement audit closing the loop on what automated checks pass. Over it all sits SuperDash, the conversational layer over programme health: which programmes are running hot against limits? which counterparties are slowing payment? what failed in last night's file? — asked in plain language, answered from the live book.
At SCF volumes, one file is the stress test. A programme should grow the bank's assets, not its operations headcount.
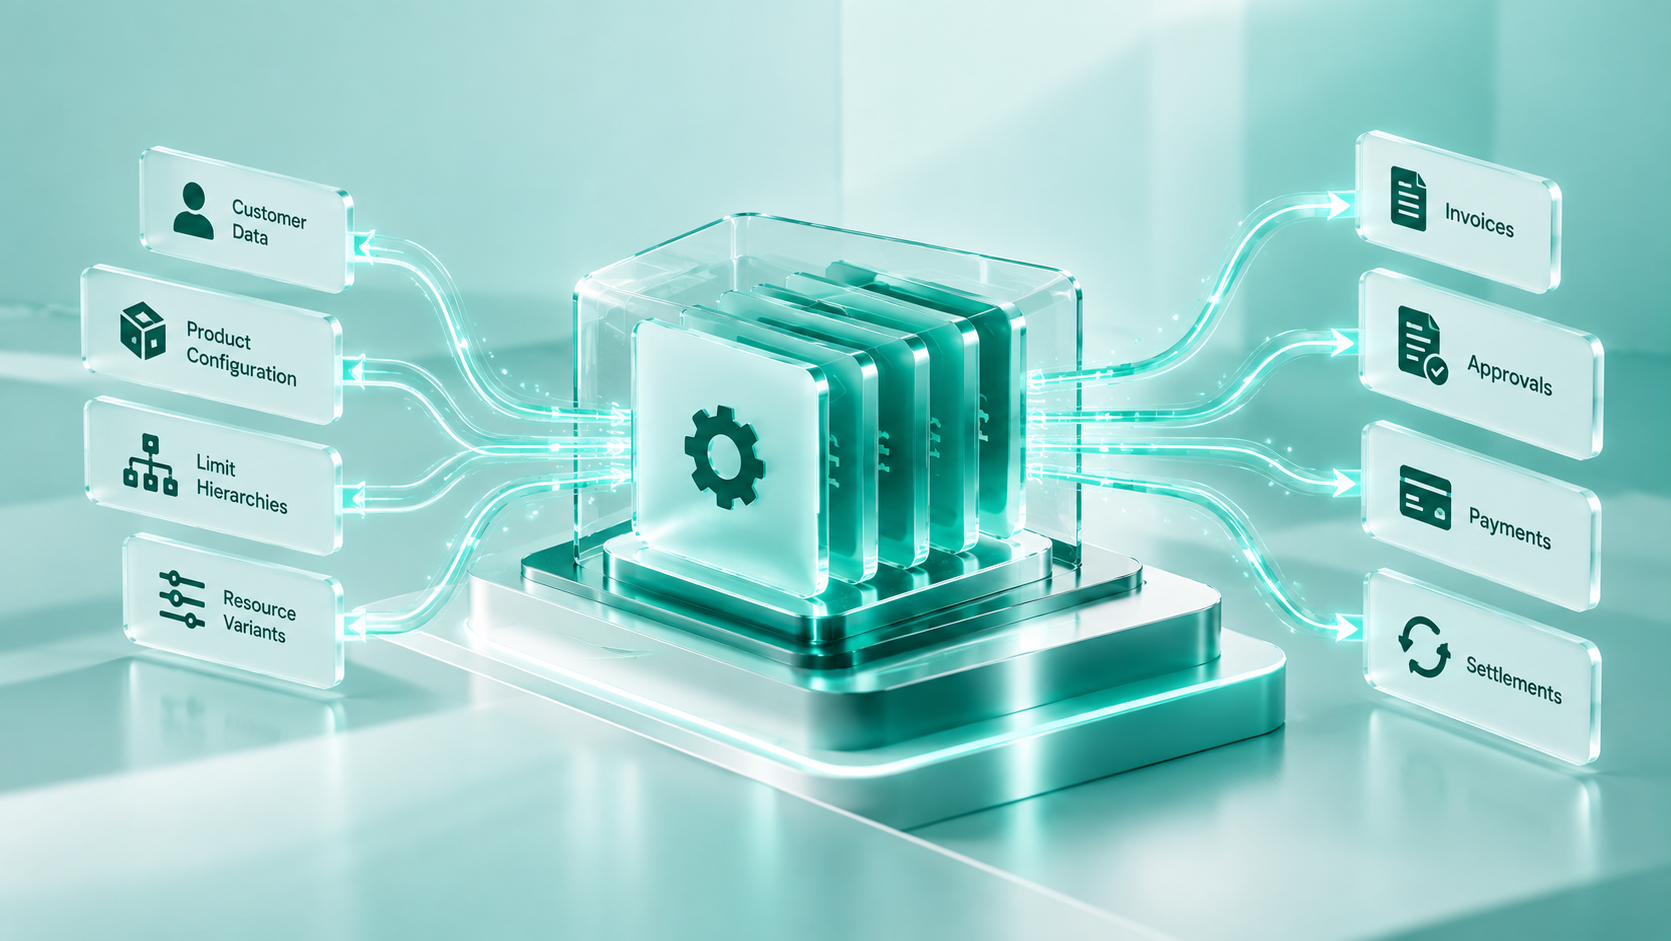
Every structure on this page — the recourse variants, the limit hierarchies, the settlement flows — is configured on the product factory, not custom-built: a new anchor programme launches in days on the platform the bank already runs, and the tenth programme costs a fraction of the first. The anchor's ERP connection, made through VECTOR, the low-code integration studio, is the programme's data spine — invoices, approvals and payment status flowing straight from the anchor's own systems. And because SCF runs on the same customer record as cash and trade, the bank prices each programme with the whole relationship in view — the balances it holds, the flows it sees, the limits already in place.
Supply chain finance is Veefin's origin — the platform's deepest-run capability, refined across more programme structures, more anchor configurations and more high-volume files than any other part of the stack, and recognised with Euromoney's SCF industry accolade. The company has since grown into the #1-ranked provider on the IBSi Sales League Table for Wholesale Transaction Banking — so the SCF a bank buys today comes with the cash, trade and channel capability around it, in production across global and regional commercial banks, development institutions and digital-first banks in Asia, Africa and the Middle East.
An SCF programme is one mandate with several owners — and the same platform answers each of them.
| Role | What they're after |
|---|---|
| Head of Supply Chain Finance | Programmes structured as the anchor demands — every recourse, tier and settlement variant on one platform, so no deal is turned away |
| Head of Corporate & Commercial Banking | The multiplication move — one anchor mandate opening assets, balances and fee income across an entire chain of counterparties |
| COO / Operations | The ten-thousand-invoice file processed straight through — validation at the gate, reconciliation as an exception queue, a book that scales without headcount |
| CIO | Programmes configured on one chassis, integrated to the anchor's ERP through one low-code layer — no parallel SCF stack to run |
This is where the operating relationship pays out in full. Cash won the corporate's day; trade embedded the bank in its supply chains; supply chain finance monetises everything those two positions revealed — financing both sides of every invoice, reaching hundreds of counterparties through one relationship the bank already holds. Done on the right platform, it is the fastest-compounding book in transaction banking. Done on a simple one, it is a pilot that never scales. The difference is the system underneath.