MANAGE CASH & LIQUIDITY
Payments, collections, virtual accounts, liquidity and forecasting on one platform — the complete cash proposition that wins operating deposits and anchors the operating relationship. Modernised one capability at a time, against the systems you already run.
Every corporate gives one bank its daily flow — payments out, collections in, balances checked every morning. That bank holds the operating deposits: the low-cost, sticky balances that fund everything else it does. Trade earns fees and lending earns yield, but cash decides which bank the corporate runs its business through — and the bank at the centre of the daily flow becomes harder to replace with every transaction that crosses it. Win the daily flow, and the operating relationship follows.
One platform for the whole cash business — built so a bank can win the daily flow one capability at a time, not through a big-bang replacement.

The daily flow is won on completeness: every payment a corporate needs to make or receive, on one rail. Electronic and physical payments and collections — account and book transfers, domestic and cross-border, tax, bill and escrow payments, direct debits, cheques and demand drafts with positive pay, real-time and RTGS rails. A corporate whose every payment the bank can carry has no reason to keep a second operating bank.

Collections only count when the corporate knows who paid. Virtual accounts in hierarchical structures, collections- and payments-on-behalfof, automatic reconciliation and payer identification. Reconciliation is the daily pain that moves mandates; the bank that removes it wins the collections business.

Sweeps — balance-based, transaction-based, multi-bank, term-deposit and investment — notional pooling, and bilateral and multilateral netting. The corporate's surplus stays consolidated with the bank instead of scattered across competitors — and consolidated balances are the deposit franchise.

Multi-bank, multi-currency, multi-entity visibility — including positions the corporate holds elsewhere — with intelligent cash forecasting and working-capital analytics. When the treasurer's morning starts on the bank's screen, the bank owns the treasury conversation — including for money it doesn't hold yet.
Delivered across web, mobile, API and host-tohost · ISO 27001 and SOC 2 · VECTOR low-code integration into core banking, payment rails, SWIFT and ERP.
Most cash platforms report what happened. This one works ahead of the day: forecasts that learn each corporate's cash patterns and flag the gap between predicted and actual; reconciliation that clears the ordinary automatically and surfaces only the exceptions; anomalies — a duplicate payment, an unusual beneficiary, a balance moving against pattern — raised as they occur, not discovered at month-end. And over it all sits SuperDash, the conversational layer: a relationship manager or treasury officer asks in plain language — which clients' balances dropped this week? which collections failed and why? — and gets the answer, and the action, without waiting for a report to be built.
Intelligence in the flow means the bank's people spend their day on judgement — pricing a sweep structure, deepening a mandate — not on assembling the picture.
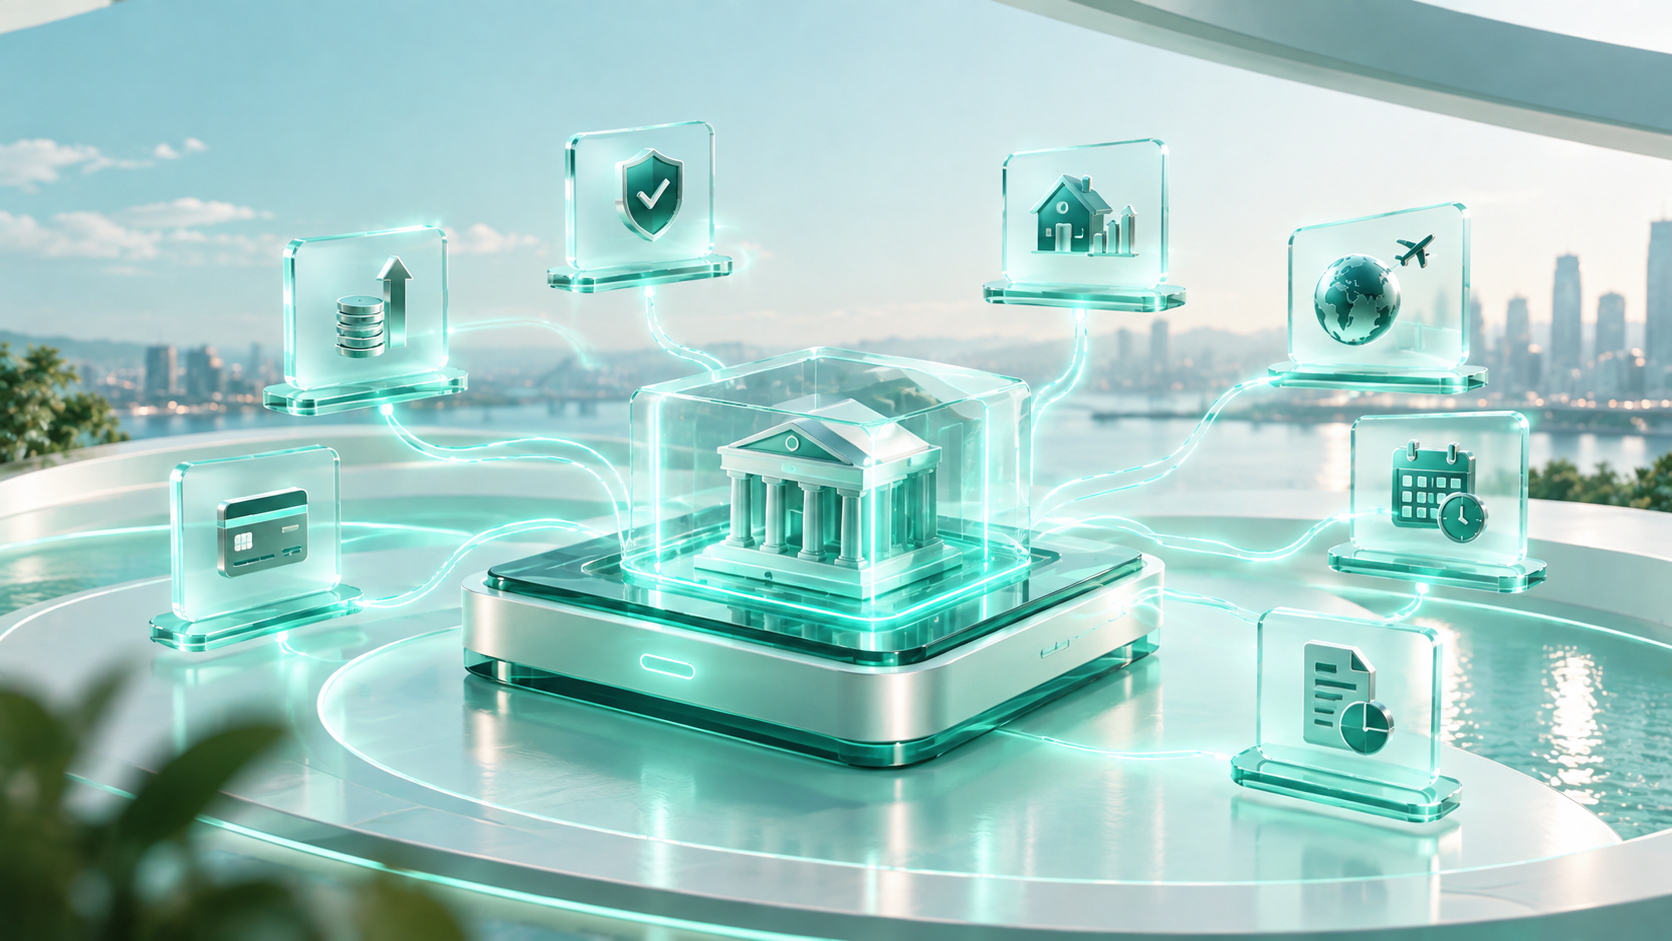
Cash management here is not a standalone treasury product wired to the rest of the bank; it runs on the same chassis as trade, supply chain finance and lending — one customer record, one limit and control model, one integration layer. VECTOR, the low-code integration studio, connects it to core banking, payment rails, SWIFT and corporate ERPs — which is what makes "one capability at a time" real rather than a slogan: each capability goes live against the systems the bank already runs, without a rip-and-replace.
Veefin leads the IBSi Sales League Table for Wholesale Transaction Banking — recognition earned in this category, against the incumbents a bank would otherwise shortlist. The platform runs in production across global and regional commercial banks, development institutions and digital-first banks in Asia, Africa and the Middle East — including institutions running several Veefin products together on one platform, which is precisely the architecture this page describes.
Winning the cash relationship is one ambition with several owners — and the same platform answers each of them.
| Role | What they're after |
|---|---|
| Head of Cash Management / Treasury Services | A cash proposition that wins mandates — complete payments, solved reconciliation, liquidity structures corporates ask for by name |
| Head of Transaction Banking | The daily flow as the anchor of the whole relationship — cash won first, trade and financing compounding on it |
| COO / Operations | Exceptions-only operations — reconciliation, payments and enquiries that run themselves at corporate scale |
| CIO | One platform for the cash franchise, integrated to core and rails through one low-code layer — capability added without a second stack |
Cash is usually where transaction-banking modernisation begins — it touches every corporate every day, and it is where operating deposits are won. Modernise it first and each flow that follows gets easier: the cash relationship strengthens trade, and trade strengthens supply-chain finance, with each step building on the record and rails of the last. The bank that runs the corporate's daily cash becomes the bank the corporate runs its business through.